Child Benefit rates in 2026/27
Child Benefit in 2026/27 is £27.05 per week for the eldest or only child and £17.90 per week for each additional child. For a family with two children that is £2,337.40 per year; for three children, £3,268.20 per year. The benefit is paid every four weeks directly into your bank account, and there is no household income limit for claiming, only the High Income Child Benefit Charge (HICBC) applies after the fact if earnings are above the threshold.
Child Benefit is not means-tested at the point of application. You can claim regardless of whether you or your partner work, and the payment does not taper off as earnings rise, instead, it is claimed in full and then partially or fully repaid through PAYE or Self Assessment if one parent's income is above £60,000. This separation of claim and repayment causes significant confusion, but it means every eligible family should at minimum register for Child Benefit even if they ultimately repay most or all of it.
How the High Income Child Benefit Charge works
The HICBC is a tax charge levied on the higher earner in the household. It is calculated on adjusted net income (ANI), essentially gross income minus personal pension contributions and Gift Aid donations. Once either parent's ANI exceeds £60,000, the charge kicks in. For every complete £200 of ANI above £60,000, 1% of the Child Benefit received is repaid (HMRC rounds the percentage, the Child Benefit total and the charge down to whole numbers). By the time ANI reaches £80,000, the entire Child Benefit amount is repaid, the effective marginal rate in the £60,000–£80,000 range is very high as a result.
Crucially, the charge is assessed on individual income, not combined household income. This means a couple each earning £55,000 (£110,000 between them) pays no HICBC at all, while a couple where one earns £80,000 and the other earns nothing repays Child Benefit in full. If both partners are over £60,000, the one with the higher adjusted net income pays the charge. This individual basis is often misunderstood and leads households to wrongly assume they are not affected. You must check whether either individual in the household, including a live-in partner who is not the child's parent, has ANI above £60,000.
The charge is paid either through PAYE, using HMRC's online service so it is collected through your tax code, or through Self Assessment, which you must use if you already send a tax return or are paying after 31 January following the tax year. Either way it is not deducted automatically: the higher earner has to tell HMRC. Failing to register can lead to penalties and unexpected tax bills going back several years, so if your ANI is anywhere near £60,000 it is worth checking your position now.
Reducing your adjusted net income to recover Child Benefit
Adjusted net income is gross income minus personal pension contributions (not employer contributions via salary sacrifice, which reduce gross pay before ANI is calculated) and gross Gift Aid donations. This means pension contributions made directly or via a personal pension plan reduce ANI pound for pound. Someone earning £65,000 who makes £6,000 of personal pension contributions has an ANI of £59,000, below the threshold, and can keep all their Child Benefit.
Salary sacrifice pension contributions work differently but are even more effective. Because they reduce the gross pay figure itself, they reduce ANI and simultaneously save income tax, National Insurance and the HICBC all at once. Someone earning £68,000 with no other income who salary sacrifices £9,000 into their employer pension scheme has an ANI of £59,000 and pays no HICBC. With two children that removes a £934 charge (40% of £2,337, rounded down), on top of £3,600 of income tax saved at 40% and £180 of National Insurance saved at 2%: about £4,714 a year from a £9,000 sacrifice. The numbers make this one of the most powerful planning opportunities for higher-rate taxpayers.
Gift Aid donations also reduce ANI. If you donate to registered charities under Gift Aid, the gross value of those donations (the amount you actually paid grossed up by basic-rate tax) is deducted from ANI. For large charitable givers near the £60,000–£80,000 band, this can make the difference between paying the full HICBC and recovering meaningful amounts of Child Benefit.
Should you still register even if you earn over £80,000?
Yes, and this is the most commonly overlooked point. Even if your ANI is well above £80,000 and you will repay all the Child Benefit, you should still register. The reason is National Insurance credits. If your household includes a parent who is not working or working limited hours, registering for Child Benefit protects their National Insurance record for State Pension purposes. Each year of NI credits for a non-working or lower-earning parent counts toward their 35-year State Pension entitlement. A parent who misses years of NI credits because they did not register for Child Benefit can find themselves with a permanently reduced State Pension.
If you are registered but do not wish to receive the payments, to avoid the obligation to file Self Assessment, you can opt out of receiving the money while keeping the NI credits active. Do this via the HMRC Child Benefit online service or by calling HMRC directly. Your income can change year to year through promotions, redundancy, reduced hours or large pension contributions; keeping the registration live means you can start receiving payments again quickly if your ANI drops below £80,000.
Budget 2026: Child Benefit overpayments and the charge
The Budget says HMRC will be able “to offset Child Benefit overpayments against High Income Child Benefit Charge (HICBC) payments” made for the same overpayment, back to January 2013 (announced, needs legislation: it takes effect when the Finance Bill becomes law).3
Nothing changes for the charge itself: the 2026-27 rules on this page still apply.
Free Child Benefit calculator 2026/27 UK (free)
Before you go
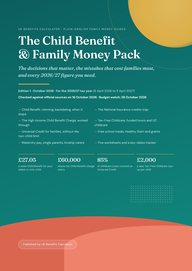
Family Money Pack
- A fill-in Child Benefit charge calculator
- A Tax-Free Childcare vs UC childcare comparison
£4.99 one-off · full refund if you ask within 14 days